Sale Agreement Deadline: Every Deadline Explained
Understand every sale agreement deadline, from the 10-day cooling-off period to suspensive conditions, extensions, and penalties. Practical tips
A buyer in France has a statutory 10-calendar-day withdrawal period after the sale agreement is notified, and the count includes weekends and public holidays. If the tenth day falls on a non-working day, the deadline moves to the next working day.
That single rule is usually the one first-time buyers hear about. Then the questions start. What happens after the cooling-off period, when does the mortgage clock begin, which dates are written into the contract, and what if one deadline slips while another is still running?
A sale agreement deadline is not one deadline, it's a chain. One date opens the next. One missed step can delay the whole file, and in some cases it can expose the buyer or seller to avoidable stress, a broken timetable, or a fight over whether the sale still stands.
Why Every Sale Agreement Deadline Matters
You signed on a Saturday afternoon, left the notary's office with a folder under your arm, and thought the hard part was over. By Monday, the file has already started a countdown, and every document seems to have its own clock. That feeling is normal, because a sale agreement deadline unfolds as several linked deadlines, each one triggering the next.
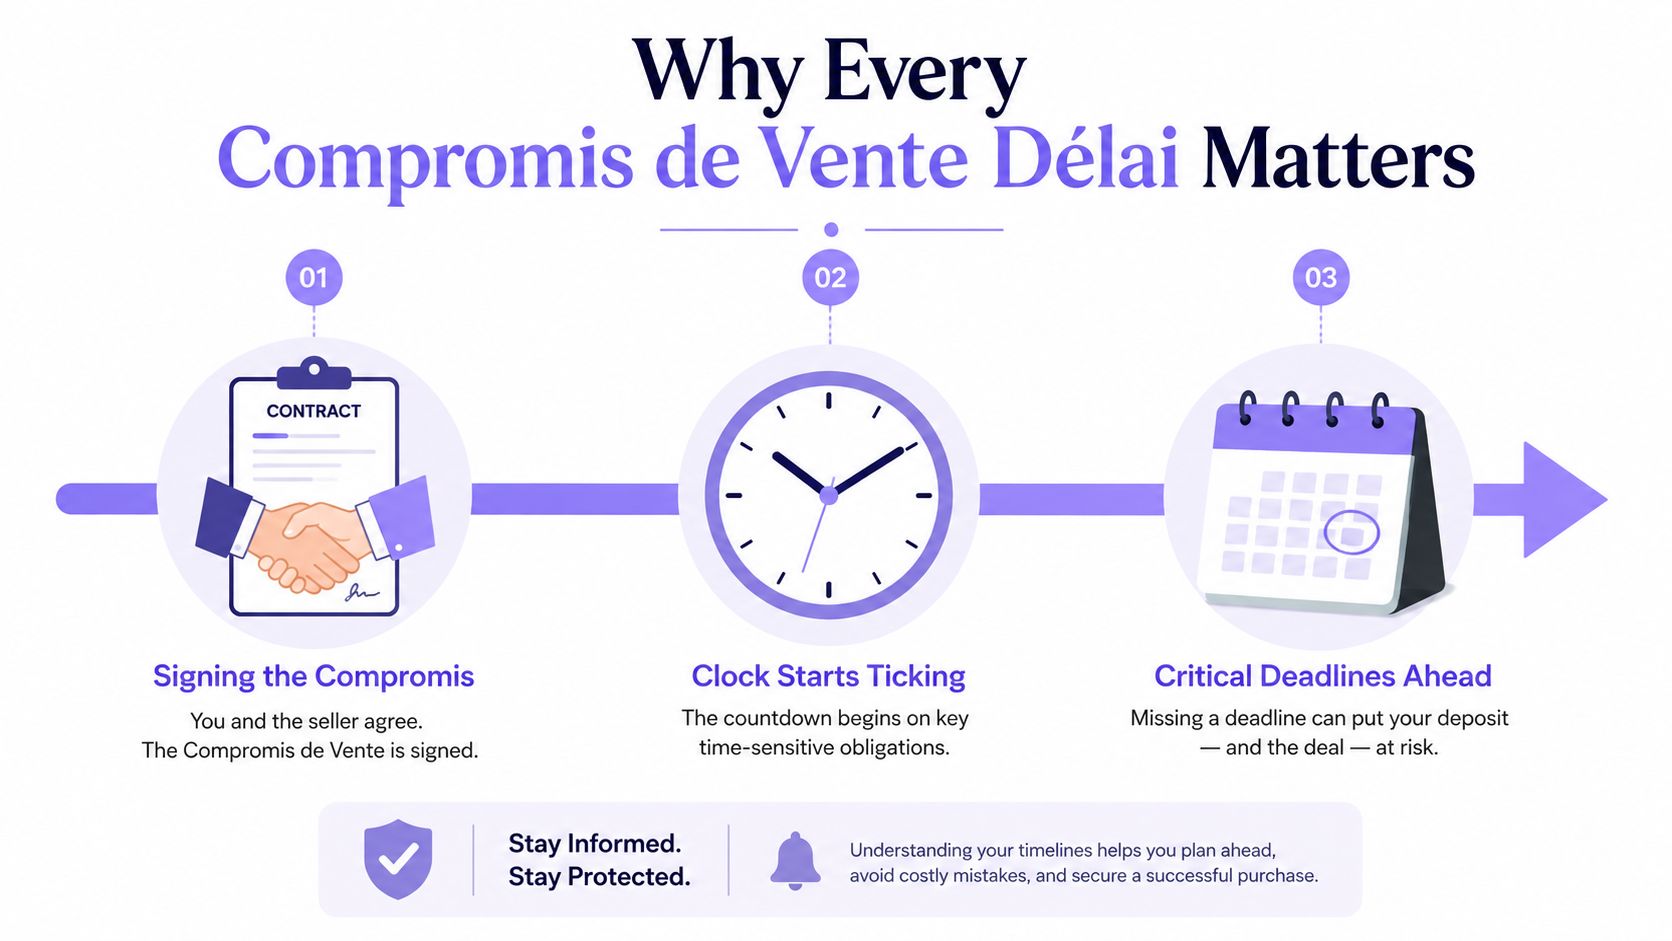
The sale works like a sequence, not a single event
First comes the cooling-off period, which protects the buyer after notification of the sale agreement. Then come the suspensive conditions, such as financing or planning checks, which decide whether the contract becomes firm or falls away. After that, the target date for the final deed of sale sets the moment when ownership transfer is completed.
That chain matters because the buyer's right to withdraw and the contract's own deadlines are often confused. They do different jobs. The withdrawal period is a legal protection for the buyer, while the later dates are usually written into the compromise itself and shape the rest of the transaction.
Practical rule: if you confuse the withdrawal window with the signing date for the final deed, you can miss the deadline that controls the transaction.
A compromise is not “the sale done”, it is “the sale scheduled, if each condition is met on time”. One late step can push the next one back, especially if the notaire still needs documents or if the bank replies after the contract deadline. The file then works less like a single appointment and more like a row of dominoes, where each piece depends on the one before it.
For a plain-language model of the first-stage agreement, the model promise of sale helps show how these pre-contract documents are usually framed. Once the sequence is clear, the deadline chain feels easier to read and manage.
The 10-Day Cooling-Off Period Explained
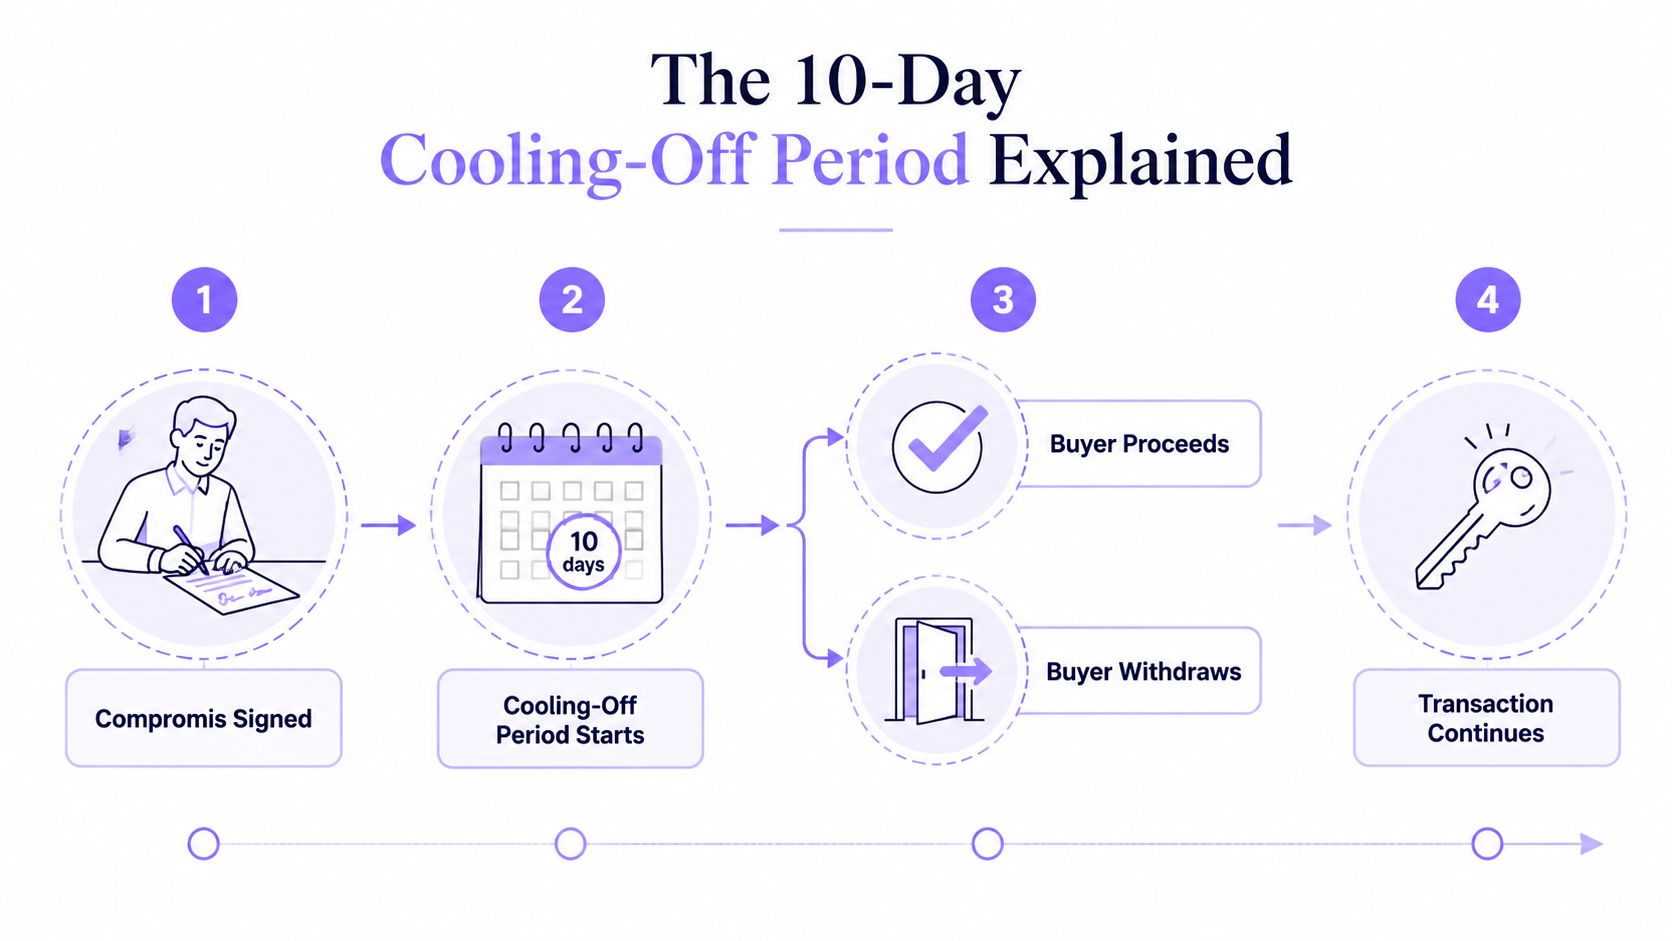
The buyer's withdrawal right is a fixed legal protection for a non-professional buyer of residential property. Service-Public confirms that the buyer has a 10-calendar-day withdrawal period after the sale agreement is notified, a rule in force since the Macron reform of 8 August 2015, which extended the earlier 7-day period to 10 days, and that the count starts the day after the first presentation of the registered notice or the day after hand delivery, with weekends and public holidays included. If the tenth day falls on a non-working day, the deadline moves to the next working day. Service-Public's explanation of the withdrawal period is the reference point for this rule.
How the count really starts
The easiest way to understand it is with a calendar. If the notice is handed over on Tuesday, day 1 starts on Wednesday. Wednesday becomes the first day of the count, Thursday the second, and so on, even if a weekend falls inside the period.
That detail matters because people often think only working days count. They don't. The law counts calendar days, so Saturday and Sunday are included. If the tenth day lands on a Sunday or a public holiday, the end of the deadline rolls to the next working day.
How to withdraw correctly
The buyer doesn't need to justify the decision. A registered letter is the normal way to make the withdrawal clear and provable. Once the notice is sent within the legal period, the buyer is out, and the contract does not continue on that basis.
The seller has no matching cooling-off right. That imbalance is deliberate, and it is one reason the buyer's signature carries a protective delay while the seller's commitment is immediate.
The section from Wispra's guide to the purchase agreement is useful if you want a broader legal picture of how these pre-sale documents usually work, especially when you're comparing the French compromise with other buying frameworks.
After that 10-day window closes, the file moves into a different phase. The question is no longer “can I walk away freely?”, it becomes “have the contractual conditions been met, and are we ready for the final deed?”. That's where the next deadlines begin.
Deadlines Attached to Suspensive Conditions
Once the cooling-off period ends, the compromise enters a second clockwork phase. The sale now depends on its suspensive conditions, meaning clauses that say the deal continues only if a specific event happens before a specific date. Each deadline stands on its own, so the file must be read clause by clause.
The three clauses buyers see most often
The most common one is the mortgage condition. The buyer must file the loan request within the period set in the contract, then wait for the bank's reply. If the financing is accepted on time, the sale can keep going. If the loan is refused in the way the clause requires, the compromise may fall away.
Other checks can also sit in the file. These may involve urban-planning verification, pre-emption rights, or title checks linked to the seller's paperwork. A deadline for one clause does not extend the others, just as one open door does not open the next door in a corridor.
The contract becomes firmer only when its conditions are lifted. Until then, everyone is waiting on a chain of linked steps.
For a clear overview of how purchase agreements are usually organised, the guide to the purchase agreement is a useful companion read. To see why the seller's file can shape the pace of the sale, the documents needed to sell a property is also helpful.
Why each deadline has to be read on its own
A mortgage clause often has two separate layers in practice. First, the buyer must submit the application. Then the bank needs time to examine the file and answer. If the application is late, the whole sequence tightens. If the bank is slow, the parties may need an amendment instead of waiting informally.
The same logic applies to land, planning, or pre-emption checks. If a public authority has a response window, the sale cannot be treated as ready until that window is handled correctly. A compromise is therefore less like a single promise and more like a row of gates. Each gate must open before the next one can be crossed.
When Deadlines Are Missed or Need Extending
A missed deadline does not always mean the sale collapses, but it does change the legal position. The result depends on what deadline was missed, what the clause says, and whether both parties agreed to move the date.
Deadline outcomes at a glance
| Situation | What Happens | Your Next Step |
|---|---|---|
| The condition is met on time | The sale can continue toward the final deed | Keep collecting documents and prepare for signing |
| The bank refuses the loan in line with the clause | The financing condition may fail and the file may stop | Notify the notaire and keep written proof of the refusal |
| The bank needs more time | The timetable no longer matches the contract | Ask for a signed extension before the deadline passes |
| Both parties agree to move the date | The contract can continue on the new timetable | Sign an amendment, not just an informal message |
What actually protects you
An extension normally needs a signed amendment, often called an avenant. That written change matters more than a friendly email because the contract date, not the conversation, is what controls the file. If the date changes, the paper needs to change with it.
A buyer who misses a financing deadline can lose the protection of the clause if the file was not handled the way the compromise required. A seller who waits past the agreed date without formal extension may face a challenge if the buyer insists the contract should still be honoured. The point is simple, and not very glamorous, written proof wins.
For practical coordination ideas, deadline management tips for 2026 can be a useful reminder that good timing is mostly about visible tracking, not memory. In property work, that principle is even more important because one unclear date can unsettle the whole chain.
A Sample Timeline From Signing to Final Deed
A typical file becomes much easier to understand when you follow one buyer from start to finish. The exact dates always come from the contract, but a realistic sequence helps you see how the pieces fit together.
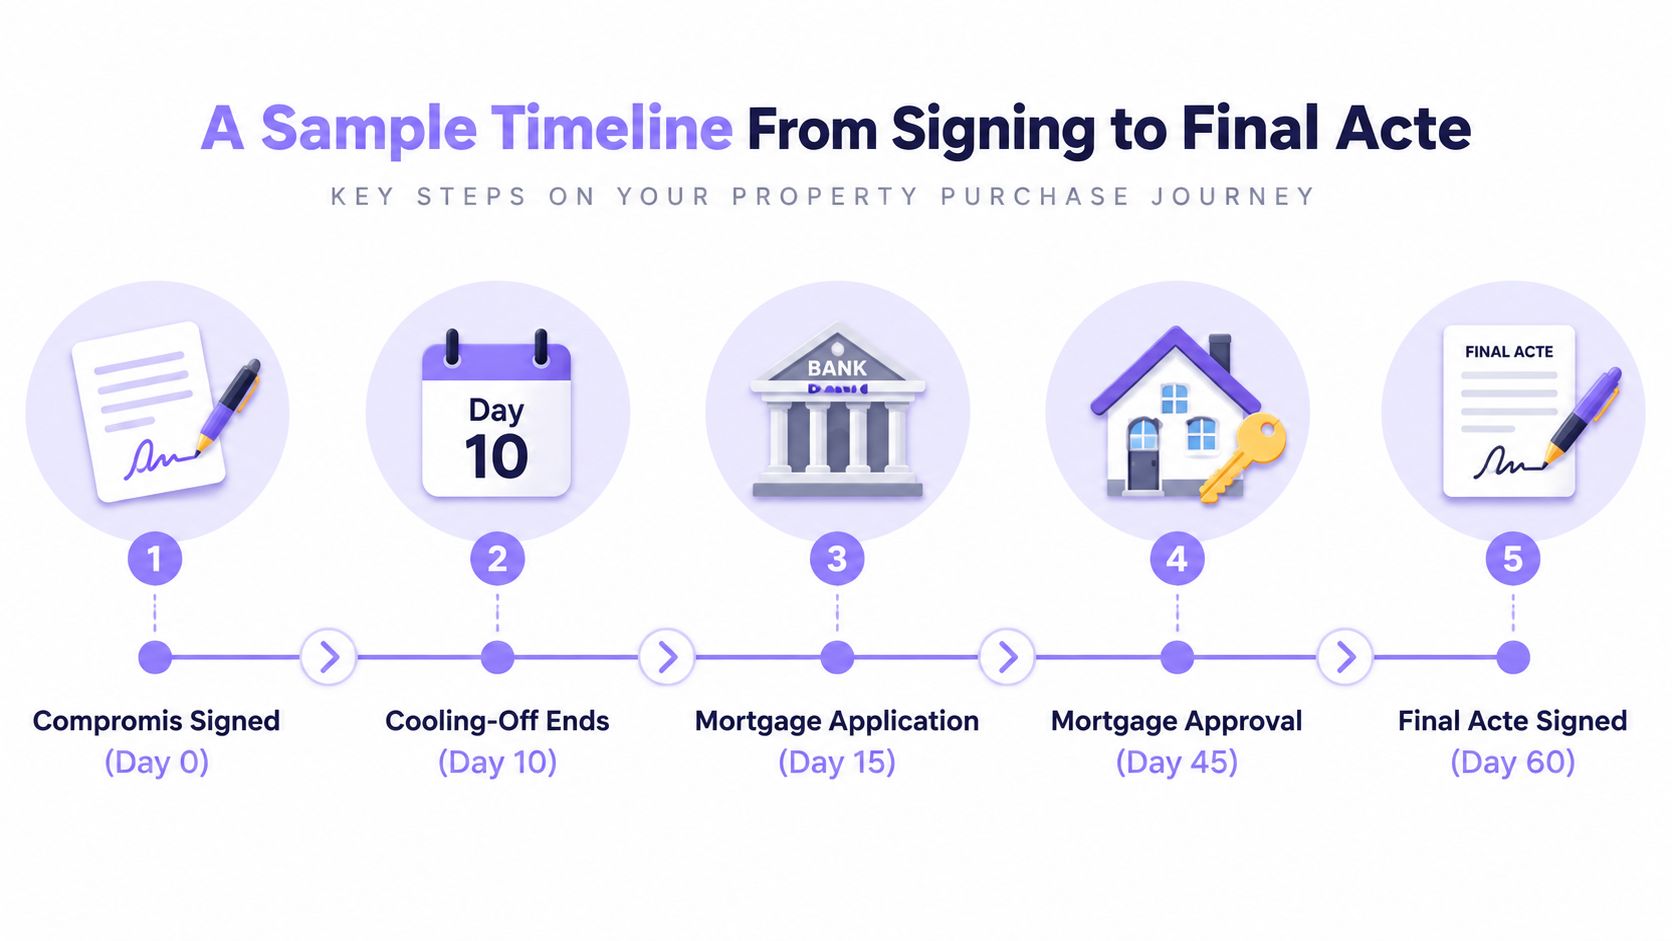
A simple, plausible sequence
Day 0 is the signature of the sale agreement. The buyer receives notice shortly after, and the 10-day cooling-off period begins the next day. If the buyer stays in, the file moves on to the financing phase, where the loan application is filed and the bank starts its review.
Later, the lender issues its answer, and the suspensive condition is either lifted or not. While that is happening, the notaire is also checking the title file, the seller's papers, and any administrative points that still need clearance. Only once the file is clean can the final deed be scheduled with confidence.
For a broad view of how long property transactions can take in practice, this guide on selling an apartment gives useful context on why property calendars rarely move in a straight line.
Clauses you may recognise in your own contract
A compromise often contains wording like this in substance, even if the exact phrasing differs:
- “The buyer must apply for financing within the contract deadline.” That means the loan request is not optional or open-ended.
- “The sale is subject to obtaining the required financing.” That means the deal still depends on the bank's answer.
- “The parties may sign the final deed once all conditions are fulfilled.” That means the notaire will not finalise the transfer until the file is ready.
A contract date looks fixed on paper, but in real life it only holds if every linked step is completed in time.
That is why the final deed often feels far away on signing day. The sale agreement opens the path, but each later stage, notification, financing, and notarial check, has to land in the right order before the keys can change hands.
How to Track and Manage Every Deadline
The biggest mistake is assuming the notaire will chase every date for you. In reality, the notaire organises the file, but the parties still need to watch the moving parts closely. Deadlines do not stretch just because everyone is busy.
Build one written timeline on day one
Start with a single page or spreadsheet the day you sign. Put the notification date, the end of the withdrawal period, the financing deadline, and the target date for the final deed in one place. Add a reminder one week before each milestone so you can act before panic starts.
Keep proof of every key step. Save loan emails, bank receipts, signed amendments, and any written confirmation that a condition has been lifted. If you later need to show what happened and when, that record matters more than memory.
Separate buyer tasks from seller tasks
The buyer should watch the cooling-off window, the loan file, and any obligation to respond to the notaire quickly. The seller should track the documents needed to prove title and keep the file moving. Both sides should check whether the contract sets a real date or just an estimated target.
A short rule helps here. If a deadline changes, the change needs to be written down and signed by the right people. An email chain can help the discussion, but it should not replace the amendment.
Keep the notaire informed, but don't delegate the calendar
The notaire should be told immediately if the bank delays, a document is missing, or a public authority has not replied. That said, the calendar still belongs to the parties. If you wait for someone else to notice the deadline first, you may already be too late.
The cleanest habit is to check every date against the contract itself, then update your own list the same day. That simple routine prevents most disputes before they start.
Key Takeaways for a Stress-Free Deadline Chain
A sale agreement deadline works best when each date is read on its own. The buyer's 10-day withdrawal period begins with notification, then the contract's own dates take over, one by one.
Check the clause in the sale agreement itself, not the timing people usually mention in the market. A financing deadline, a suspensive condition, and the date for the final deed each follow a separate clock. If one date moves, the change should be written and signed. If a condition is met, keep the proof.
A short checklist helps keep the file in order:
- Note every deadline on signing day.
- Count the withdrawal period from notification.
- Use the contract clause, not an estimate.
- Record any extension in a signed amendment.
That way, you always know which obligation is due, which proof belongs to it, and what document should sit in the file if anyone later asks.