Plus-Value Immobilière Calcul: A Step-by-Step Guide
Master plus-value immobilière calcul with formulas, deductible costs, abatement schedules, exemptions, and worked examples to estimate your French property tax.
You're at the notary's office, the sale price looks excellent, and then the draft statement shows a plus-value immobilière tax bill far above what you expected. The surprise usually comes from treating the calculation as a simple sale price minus purchase price exercise. In practice, acquisition costs, eligible works, sale expenses, ownership duration, residence status, and the high-gain surcharge can all change the result.
The calculation is technical, but it's manageable if you work through it in the right order. This guide focuses on the adjustable inputs that sellers often overlook, with worked examples showing why two owners who sell similar properties can face very different bills.
How the Taxable Plus-Value Is Calculated
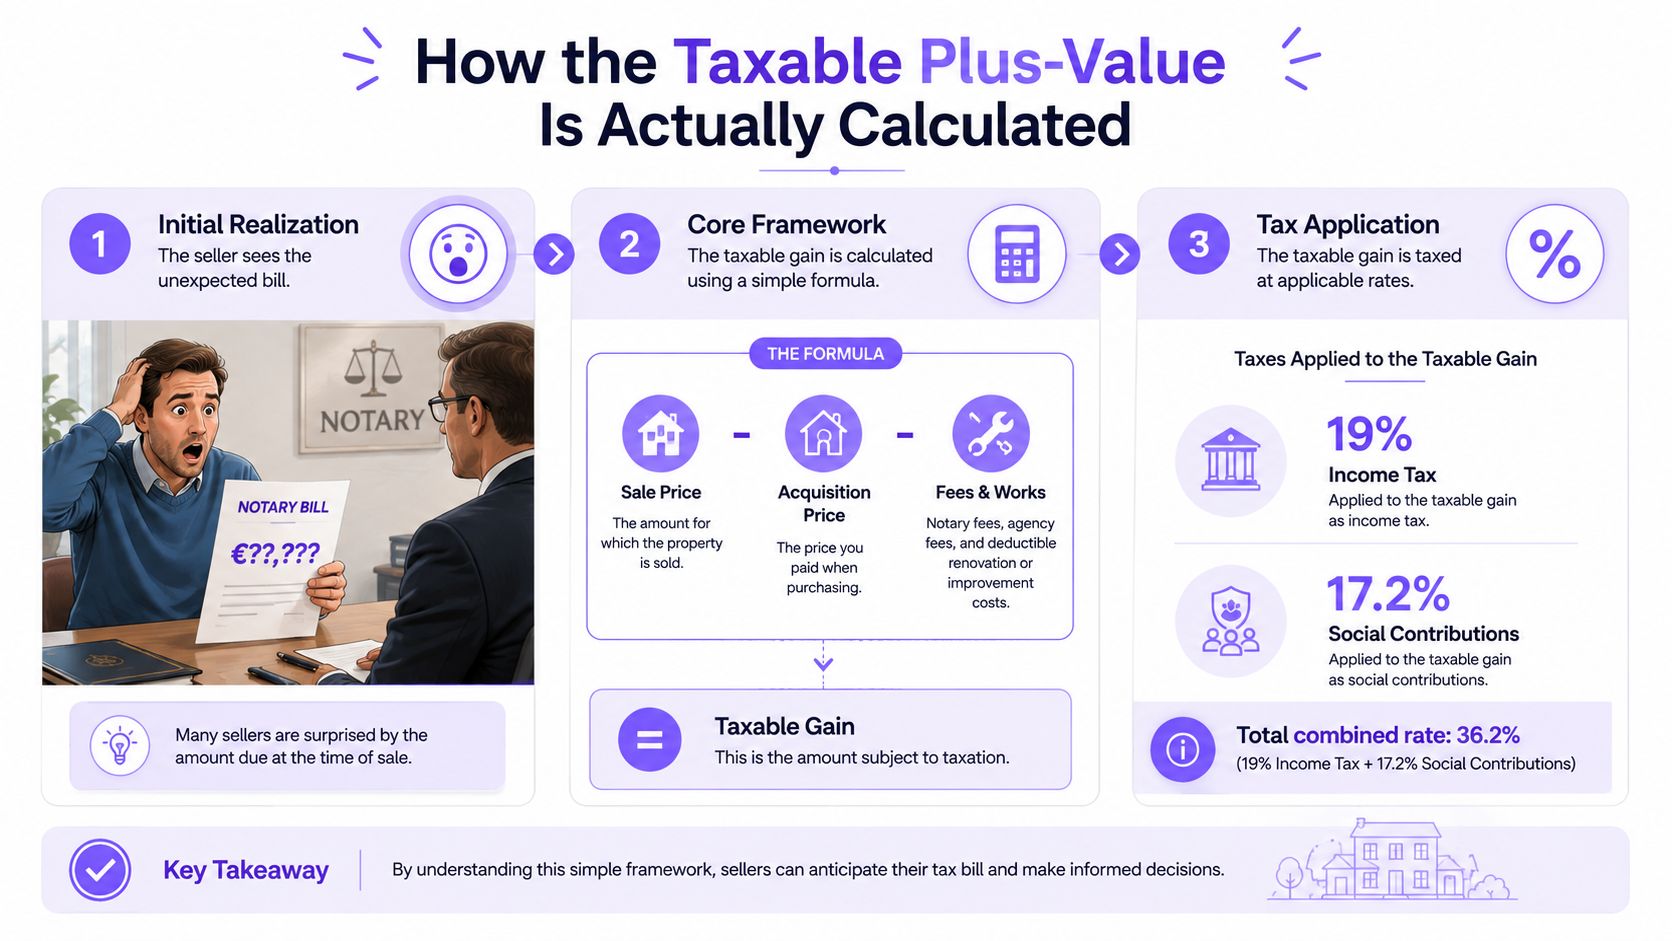
At the notary appointment, the completion statement can show a taxable gain very different from the apparent difference between the sale and purchase prices. The notary calculates adjusted amounts first, then applies the relevant reliefs. That order determines the bill.
The starting formula is:
Taxable gain = adjusted sale price minus adjusted acquisition price
Qualifying sale expenses reduce the sale price. Eligible acquisition costs and works increase the acquisition price. Only after those adjustments does the holding-period relief apply.
The headline rates are only the starting point
For a taxable private-property gain in France, income tax is 19% and social contributions are 17.2%. The combined burden is 36.2% before holding-period relief. Treat that figure as a starting rate, not as a shortcut applied to the raw price increase.
A principal residence may be exempt. For a secondary residence or investment property, the result can change through acquisition-cost choices, eligible works, and duration-based abatements. The notary's completion statement should show how those inputs were handled.
Practical rule: Calculate the adjusted gain before applying the rates. Applying 36.2% directly to the difference between sale and purchase prices will often overstate the bill.
Use this sequence:
- Establish the sale price and deduct qualifying sale expenses.
- Establish the acquisition price and add eligible acquisition costs.
- Add qualifying works, or use the applicable flat works allowance.
- Calculate the gross gain.
- Apply the separate income-tax and social-contribution abatements.
- Check whether the remaining taxable gain crosses the surtax threshold.
The adjustable inputs often matter more than the headline rates. Choosing documented costs or a flat allowance can change the taxable base, while the holding period can reduce it further. Sellers comparing systems can also consult this CGT discount explained for small business for a broader explanation of why tax calculations distinguish between a raw gain and an adjusted taxable gain.
Choosing Your Acquisition Cost Options
The acquisition basis is where the calculation becomes a decision exercise. You're not always locked into the amount shown on the purchase deed. French guidance allows qualifying acquisition costs and certain works to increase the basis, reducing the gain that remains taxable.
For an acquisition made for consideration, the seller generally compares documented acquisition expenses with the flat allowance of 7.5% of the acquisition price. The practical choice is between proof and simplicity.
| Cost type | Actual option | Flat allowance option | Best when |
|---|---|---|---|
| Acquisition costs | Use justified notarial fees, registration duties, and eligible intermediary fees | Use 7.5% of the acquisition price | The flat amount is higher than the documented total |
| Works | Use eligible, documented invoices | Use 15% of the acquisition price after more than 5 years of ownership for a built property | Invoices are missing, low, or difficult to qualify |
| Sale expenses | Deduct qualifying costs actually borne by the seller | No general flat substitute | Diagnostics, mortgage release costs, or eligible agency fees are documented |
The 7.5% option applies to the acquisition price, not the eventual sale price. If the documented costs produce a larger uplift, the actual route may be preferable. If the paperwork is incomplete or the documented costs are lower, the flat option can be more efficient.
Works require a separate comparison
For a built property sold after more than 5 years, the seller can generally choose the 15% works allowance instead of using actual qualifying invoices, as reflected in the Notaires de France guidance on property capital gains. The allowance is particularly useful where the owner carried out limited work, used incomplete records, or handled improvements personally.
You can't add the 15% allowance on top of actual works invoices. Choose one route. Actual works may win where substantial eligible renovation is fully documented, while the allowance often wins where invoices are absent or the work total is modest.
A missing invoice can be more expensive than a disappointing sale price. Compare the real-cost and flat-allowance routes before the notary prepares the final statement.
Sale-side costs are easy to overlook. Documented diagnostics, mortgage release expenses, and an agency commission contractually borne by the seller may reduce the sale price used in the calculation. Keep the invoices and proof of payment, rather than assuming the notary will locate every item.
For broader practical preparation around an apartment purchase, the guide to buying an apartment can help you organise the deed and cost records that later support the calculation.
Applying Holding-Period Abatements
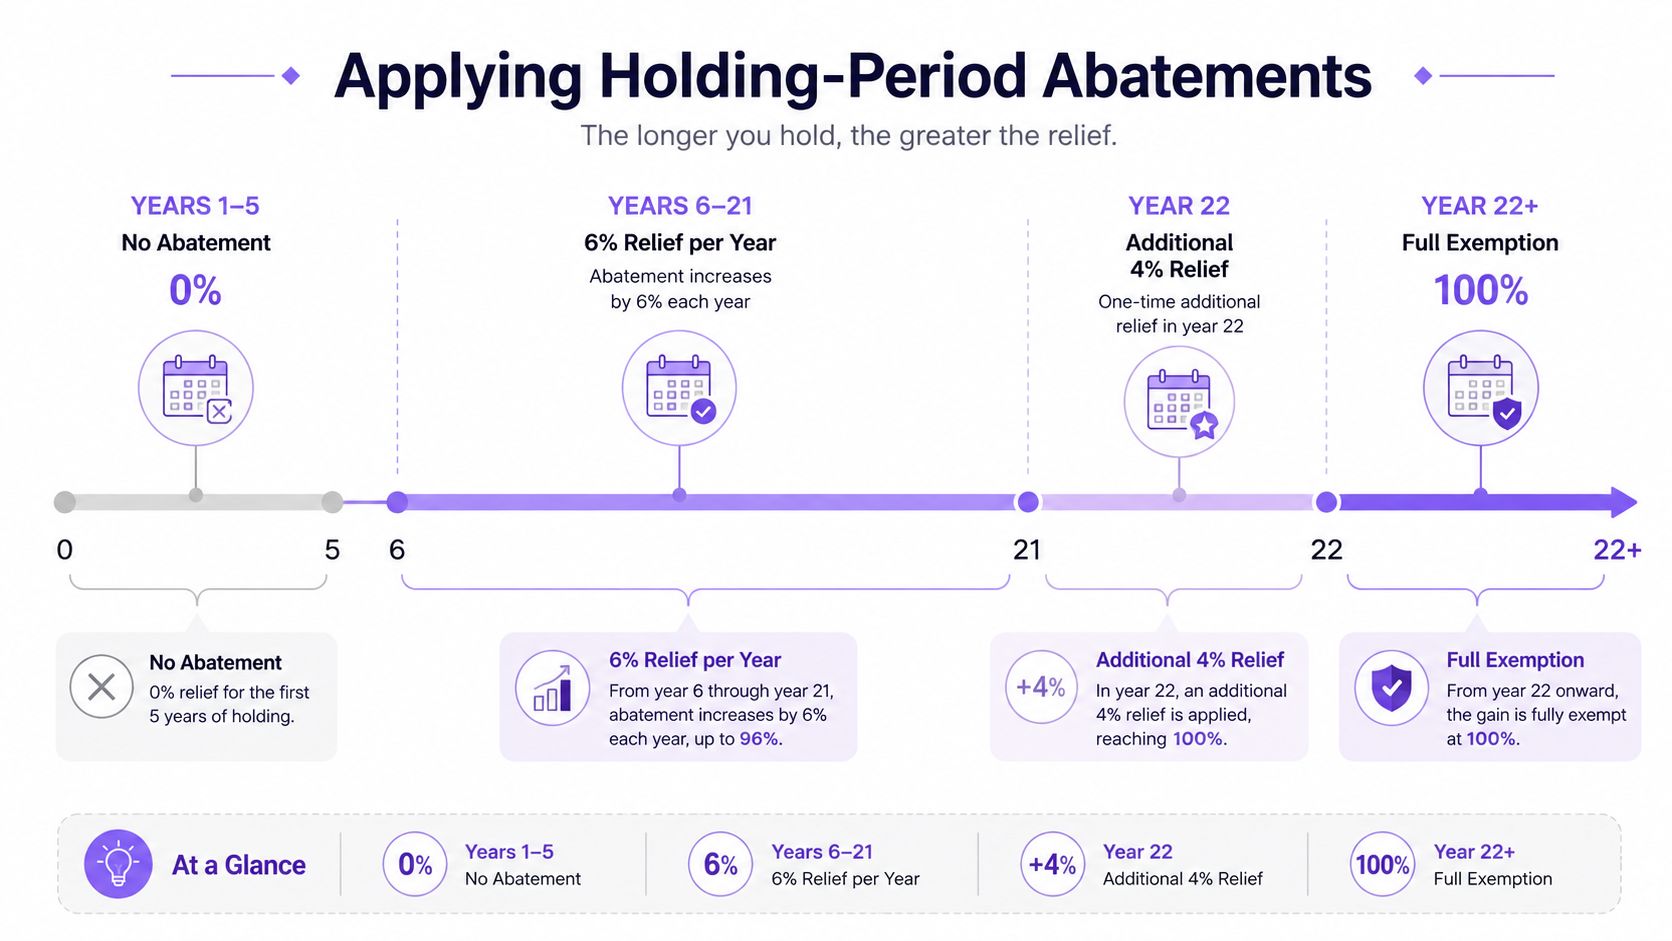
For a taxable second home or investment property, ownership duration can change the final bill more than the headline tax rates suggest. The administration applies separate schedules to income tax and social contributions, so the same holding period produces two different taxable amounts.
There is no duration abatement during the first 5 years. From years 6 to 21, the income-tax relief is 6% per year, followed by an additional 4% in year 22. Income-tax exemption is reached after 22 years of ownership.
Social contributions follow a slower schedule. Relief is 1.65% per year from years 6 to 21, then 1.60% in year 22, followed by 9% per year from year 23 onwards. Full exemption from social contributions is reached after 30 years under French law.
The schedule at a glance
| Years of ownership | Income tax abatement | Social contributions abatement | Resulting relief |
|---|---|---|---|
| Years 1 to 5 | 0% | 0% | No duration-based relief |
| Years 6 to 21 | 6% per year | 1.65% per year | Relief grows under separate schedules |
| Year 22 | Additional 4% | Additional 1.60% | Income tax reaches full exemption |
| Years 23 to 30 | Full income-tax exemption | 9% per year | Social-contribution relief continues |
| After 30 years | Full exemption | Full exemption | No standard tax remains on the gain |
Each percentage applies to the taxable gain for its own tax component. The rates cannot be combined into one blended deduction. A seller may therefore reach full income-tax exemption while still owing social contributions until the later threshold.
The important window between 22 and 30 years
The period after 22 years but before 30 years often produces an unexpected result. Income tax has ended, while social contributions remain payable on the part of the gain not yet covered by the social-contribution abatements.
The completion date can therefore affect the calculation. A seller approaching a new duration bracket should ask the notary to compare the result using the legally relevant ownership date and the planned completion date. A change in market value is only one part of that decision. The applicable holding-period bracket can also alter the bill.
The Notaires de France explanation of the plus-value rules confirms that the schedule is stepwise, with different treatment for each tax. A calculator that displays one overall relief percentage can therefore give a misleading impression of the amount due.
Exemptions and the High-Gain Surtax
The standard calculation doesn't apply uniformly to every property. Classification comes first. A sale of the seller's habitual and effective principal residence is treated very differently from a sale of a holiday home, a rental property, or another investment asset.
Principal residence status
A principal residence is fully exempt from both income tax and social contributions, with no minimum holding period, provided it is the seller's habitual and effective home at the time of completion. The exemption is therefore not merely a label the seller selects on the tax form. The factual residence status is the key control point.
Useful evidence can include utility bills, insurance records, correspondence, and other documents showing that the property was occupied as the seller's normal home. A secondary residence or rental asset doesn't become exempt merely because the owner stayed there occasionally or intended to move back.
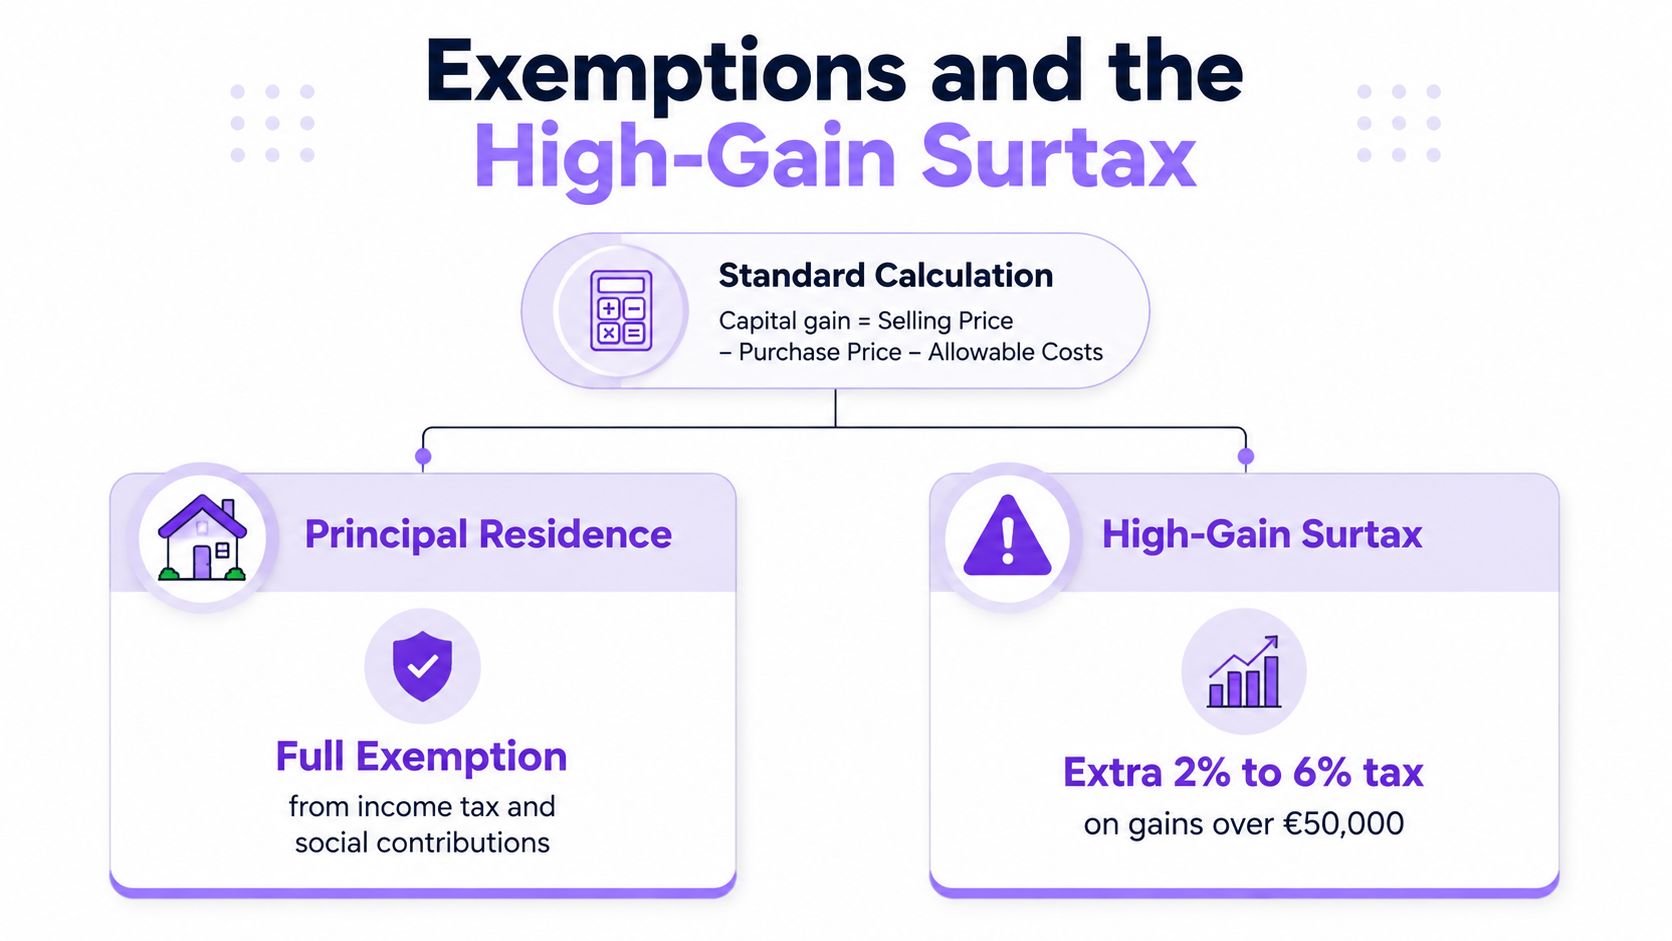
If the exemption doesn't apply, the ordinary framework returns. The gain may then be subject to 19% income tax and 17.2% social contributions before abatements, with the acquisition and disposal adjustments dealt with first.
The surtax sits on top
A separate progressive surtax applies when the net taxable gain exceeds €50,000. Its rates range from 2% to 6%, depending on the amount, and it is added to the standard income tax and social contributions. The Notaires de Paris calculation guidance describes this as an additional layer for large gains, not a replacement for the ordinary rates.
The threshold concerns the taxable gain after the applicable adjustments and duration relief, not necessarily the raw increase between purchase and sale. That distinction matters. A substantial gross gain may be reduced by acquisition costs, works treatment, sale expenses, and holding-period abatements before the surtax test is made.
Check the net figure, not the headline gain. The surtax question belongs near the end of the calculation, after the permitted reductions.
Secondary residences and investment properties usually remain within the taxable regime unless another exemption applies. Inherited and donated properties require additional care because the reference acquisition value comes from the relevant inheritance or donation documentation, rather than a straightforward purchase price. That value and the associated costs should be verified with the notary before any sale strategy is chosen.
A Worked Example From Purchase to Final Tax Bill
Consider a seller disposing of a secondary residence, not a principal home. The property was bought for €200,000 and later sold for €268,000. The seller has documented disposal costs of €450 for diagnostics and €800 for mortgage release, both borne personally.
The adjusted sale price is therefore €266,750. The seller's documented acquisition costs are €13,200, but the 7.5% flat allowance on the €200,000 acquisition price produces €15,000, so the flat route is more favourable.
The property is a built asset. Once it has been held for more than 5 years, the seller can use the 15% works allowance, equal to €30,000, instead of actual works invoices. The adjusted acquisition basis becomes:
€200,000 + €15,000 + €30,000 = €245,000
The resulting gross gain is:
€266,750 minus €245,000 = €21,750
Because the net taxable gain is below €50,000, the high-gain surtax doesn't apply. Before any duration relief, the two standard components are:
| Component | Calculation | Amount |
|---|---|---|
| Income tax | €21,750 × 19% | €4,132.50 |
| Social contributions | €21,750 × 17.2% | €3,741 |
| Combined standard burden | Before any duration relief | €7,873.50 |
For a practical overview of the wider issues affecting the sale of a rental property, see this investor guide to rental property taxes. It's particularly useful when the property has been held as an investment rather than occupied as a home.
The example shows why the input choices matter. Without the €15,000 acquisition-cost allowance and €30,000 works allowance, the taxable gain would be higher. With the adjustments, the seller's calculation starts from the legally adjusted basis rather than the original price paid.
Before marketing a property, sellers can also use this guide to selling a house to organise the transaction timeline and supporting documents.
Documents to Gather and Mistakes That Cost Money
The notary can apply the rules, but the seller must usually provide the evidence that supports the chosen calculation. A complete file makes it easier to compare actual costs with flat allowances and reduces the risk of leaving an admissible deduction out.
Build the file before the sale
Gather these documents early:
- Original purchase deed: Confirm the acquisition price, transaction type, and exact date.
- Notary and registration statements: Identify the acquisition costs that may be used under the actual-cost route.
- Works invoices: Keep dated invoices that identify the property and the contractor.
- Residence evidence: Retain utility bills and similar records supporting habitual occupation where a principal-residence exemption is claimed.
- Sale-cost proof: Collect diagnostics invoices, mortgage release records, and any agency agreement showing who paid the commission.
- Inheritance or donation paperwork: Use the value and costs recorded in the relevant deed or declaration, rather than reconstructing a fictional purchase price.
The practical reason for this checklist is simple. The calculation may be correct in theory, but an unsupported cost can't reliably improve the taxable basis. If the records are incomplete, compare the flat options before assuming actual costs will be accepted.
The errors that recur at appointments
The most expensive classification mistake is treating a rental or secondary property as a principal residence. The fix is to establish the property's actual use at completion and discuss any change of occupation with the notary before signing.
A second error is losing renovation invoices. Sellers then either abandon potentially useful actual costs or fail to compare them with the 15% works allowance available after more than 5 years for a built property. A third is counting the same works twice, especially where an expense has already been used elsewhere for income-tax purposes.
Finally, owners often count holding duration from memory. Use the dates in the deeds and ask for a calculation based on the planned completion date. The property-sale document checklist can help you organise the wider transaction file without mixing sales paperwork with the separate plus-value evidence.
For inherited or donated property, don't apply a standard purchase-price template. The reference value is tied to the succession or donation documents, and the admissible costs require specific review.
Key Takeaways Before You Sell
A reliable plus-value immobilière calcul rests on four decisions:
- Choose the acquisition-cost basis: Compare documented costs with the applicable flat option.
- Test the works route: After more than 5 years on a built property, compare invoices with the 15% allowance.
- Count the ownership period precisely: Income-tax exemption arrives after 22 years, while social contributions continue until 30 years.
- Classify the property correctly: A genuine principal residence is fully exempt, while a secondary or investment property generally requires the full calculation.
- Check the surtax: Test the net taxable gain against the €50,000 threshold after adjustments and abatements.
Pull out the deed, sort the invoices, verify the sale expenses, and calculate the exact holding period before agreeing a completion date. If the sale date can legitimately move into a more favourable duration bracket, have the notary compare both outcomes before anything is signed.
If you're preparing a sale and want a clearer, better-organised online presence for your property business, Wispra helps French businesses publish AI-optimised listings, content, FAQs, and reviews so prospective clients can find and understand your services. Visit Wispra to set up your profile without changing your website.